Malaysia's Private Credit Landscape
In Malaysia the strongest collateral a non-bank lender can hold is not an asset. It is a deduction code on a government payslip. More than 900,000 civil servants repay about RM943 million a month through salary deductions processed by Angkasa, the apex body of the cooperative movement and one of six agencies that run such deductions. Only the Accountant General's Department issues the codes that make them possible. A lender that holds a code is paid before the borrower sees the salary.
That mechanism explains most of what makes the market unusual. It is why the largest lender in the segment charges about 130 basis points less when an instalment comes off the payroll rather than out of a bank account. It is why a listed lender can run a ten-year unsecured book with a non-performing ratio of 4.3%. And it is why the main risk in Malaysian consumer credit is not a borrower's behaviour but a government circular: the 60% cap on salary deductions, which the Insolvency Department has proposed cutting.
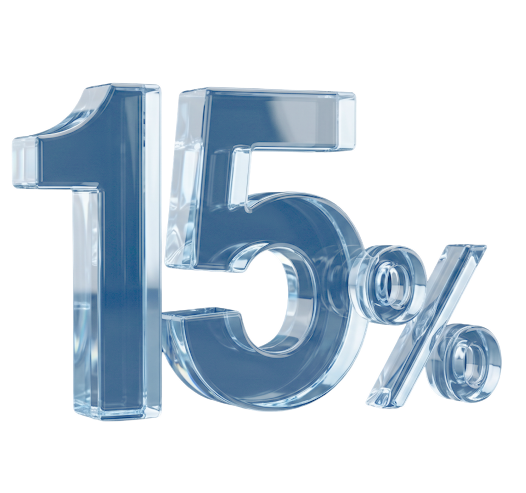
The second thing most readers get wrong is size. Malaysia's reassuring headline numbers — household impairments of 1.0%, an A-rated sovereign — describe the banking system. Household debt equals 84.8% of GDP, but only about 69.5% of GDP sits on bank balance sheets. The gap, roughly 15 percentage points of GDP or some RM300 billion, is held outside the banks, and no single dataset covers it.
The third is timing. The Consumer Credit Act 2025 came into force on 1 March 2026 and gave non-bank consumer credit a dedicated regulator for the first time. Licensing has applied since 1 June 2026, and the six-month compliance window for existing providers closes in December. A lender diligenced today is being judged against a rulebook that is still settling.
Role of Non-Bank Financial Institutions
Malaysian law splits non-bank lending across at least six statutes and five supervisors. The lender types that matter for this report are:
- Kredit komuniti (licensed moneylenders) — 4,315 licences as of September 2024, regulated by the Ministry of Housing and Local Government (KPKT) under the Moneylenders Act 1951.
- Pawnbrokers and Ar-Rahnu — 902 licensed pawnbrokers under the Pawnbrokers Act 1972, alongside Islamic gold-pawn windows run by cooperatives and development banks.
- Koperasi (credit cooperatives) — supervised by the Malaysia Co-operative Societies Commission (SKM), and the main originators of payroll-deduction financing for civil servants.
- Development financial institutions (DFIs) — Bank Rakyat, BSN, Agrobank and others, supervised by Bank Negara Malaysia (BNM) under the Development Financial Institutions Act 2002. Bank Rakyat is the country's largest personal-financing lender.
- Credit companies and specialist financiers — AEON Credit, RCE Capital, leasing and factoring firms and buy-now-pay-later (BNPL) providers. Leasing, factoring and BNPL now need a licence from the new Consumer Credit Commission.
- P2P financing platforms — Recognised Market Operators supervised by the Securities Commission (SC).
None of these lenders takes retail deposits, which is why they rely on bank lines, the bond market and private credit. No regulator publishes a consolidated loan book for the non-bank lending sector; it has to be assembled from the pieces.
All figures in ringgit (RM) unless stated. US-dollar conversions at RM4.09 per US$ (12 October 2026).
Focus of This Report
- Who lends outside the banking system, and how large that stock is, given that no consolidated dataset exists.
- The payroll-deduction channel: how it is priced, how it fails and who controls it.
- The Consumer Credit Act 2025, and the lenders that still sit outside it.
- Credit quality where it is actually measured: listed lenders, BNPL and civil-service bankruptcy data.
- How an offshore lender can participate under Malaysia's foreign-exchange rules, in a market with one of Asia's deepest local bond markets.
Key Takeaways
- Macro is not the constraint. Growth reached 6.0% in Q2 2026 with 1.9% inflation and a 2.75% policy rate. The pressure point is household leverage at 84.8% of GDP.
- About RM300 billion of household debt sits outside the banks. That is roughly 15 percentage points of GDP, and no regulator publishes a consolidated figure for it.
- Payroll deduction is the market's defining collateral. It lowers prices by about 130 basis points and keeps losses low, but its terms are set by government circular, not by contract.
- Payroll credit fails by exit, not by delinquency. Civil servants' share of new bankruptcies rose from 10% in 2021 to 14% in 2024, while national bankruptcies fell. Bankruptcy, early retirement and resignation end a deduction.
- A single regulator is arriving in phases. The Consumer Credit Act 2025 licenses BNPL, leasing and factoring from June 2026; moneylenders and pawnbrokers follow in later phases.
- Malaysian rates are quoted flat. The moneylender ceiling of 18% a year is about 31% in effective terms. Every consumer rate needs converting before it is compared.
- Hedging pays rather than costs. With ringgit rates about 125 basis points below US rates, a borrower hedging a US-dollar facility earns carry. The binding constraints are a RM100 million cap on foreign-currency borrowing from unrelated non-residents and a 10% treaty withholding tax.
The Big Picture
Malaysia grew 6.0% in Q2 2026, its strongest second quarter outside the pandemic since 2014, with headline inflation of 1.9% in August. For a credit investor that matters mainly as a buffer: employment and wages support repayment, and the risk sits in household balance sheets rather than in the cycle.
Table 1 — Core indicators
Sources: DOSM; BNM; Ministry of Finance; World Bank and DOSM via Trading Economics; S&P, Moody's, Fitch. GDP per capita is nominal GDP divided by population.
The external picture has one soft spot. S&P flagged rising private-sector external borrowing, and gross external debt reached 70.1% of GDP at end-June 2026. BNM estimates that about 60% of corporate external borrowing is intercompany loans and trade credit, which carries little rollover risk. But external debt is the reason Malaysia keeps foreign-currency borrowing limits — and those limits shape any offshore lender's facility (see The Funding Stack).
Monetary and Funding Conditions
Table 2 — Rates and banking conditions
Sources: BNM Financial Stability Review 2H 2025; BNM Q2 2026 economic release; Federal Reserve and BNM via Trading Economics.
Money is cheap in Malaysia and banks are not short of it. A 2.54% cost of funds and an 18.1% capital ratio shape the opportunity: non-bank lenders here do not exist because banks lack liquidity, but because banks avoid certain borrowers, products and ticket sizes. An offshore facility competes on access and structure, not on price.
Investor implication: with the OPR 125 basis points below the US policy rate, ringgit forward points favour a borrower that hedges a US-dollar liability. Market rates confirm it: one-year USD/MYR forward points of about −505 pips imply roughly 1.25% a year in the borrower's favour, and the one-year government yield gap (US 4.44% against roughly 3.1% in Malaysia) is about 1.3 points. A 12-month hedge therefore earns the borrower roughly 1.0–1.3% a year rather than costing it — the reverse of the Philippines or India, where hedging is a cost. The gap is narrower at the short end of the interbank curve — three-month KLIBOR has risen to 3.55%, 80 basis points above the OPR — so the borrower's actual quote from its onshore bank will vary with tenor and timing.
Credit Depth
Table 3 — Household credit
Sources: BNM Financial Stability Review 2H 2025; Prime Minister's parliamentary reply (July 2026); BIS via Trading Economics.
Malaysia's household debt ratio is one of the highest in emerging Asia, but part of that is definition. BNM's own regional comparison notes that the Indonesian and Philippine ratios cover bank lending only, while Malaysia's includes non-banks. On a bank-only basis the gap narrows by about 15 points.
Households also hold financial assets worth 2.1 times their debt. That cushion is less liquid than it looks: 68% of household financial assets are pension savings in the Employees Provident Fund (EPF) and bank deposits, and EPF balances are largely locked until retirement. The borrowers who reach non-bank lenders are typically the ones whose buffer sits in the EPF, not in the bank.
Structure and Size of the Non-Bank Sector
There is no published figure for Malaysia's non-bank lending sector, and the obvious candidate is the wrong one. BNM's "NBFI" category — RM3.3 trillion of assets in 2023, up from RM2 trillion a decade earlier — follows the Financial Stability Board definition. It includes development banks, insurers, takaful operators and fund managers. Most of it is not lending at all.
The measure that matters is the household-debt gap. BNM's aggregate household debt covers loans from banks, DFIs and non-bank lenders; the banking-system series covers banks only. The difference — 84.8% versus about 69.5% of GDP — is the non-bank household credit stock: roughly 15 percentage points of GDP, or about RM300 billion. BNM's own review for the first half of 2024 showed the same gap (83.8% versus 69.2%), so it is structural, not a statistical blip.
BNM's series covers lending by banks, DFIs and "major non-bank financial institutions", a group it has said includes LPPSA, the public-sector home financing board. The residual therefore sits largely with DFIs led by Bank Rakyat, LPPSA and the cooperative movement. Private non-bank lenders — credit companies, moneylenders, pawnbrokers, BNPL providers — are a minority of it, and the only part open to private credit.
Table 4 — The non-bank credit map
Sources: BNM; The Edge; Malay Mail; company filings; KPKT via FMT; SC Annual Report 2025. Vintages differ by row; Bank Rakyat's personal-financing split is from its June 2025 interim statements, licence counts are the latest published (September 2024).
Where the Flow Goes
The payroll channel is also where flows move fastest. After the first phase of the civil-service pay rise in December 2024, monthly personal-financing disbursements to civil servants averaged RM6.4 billion across December 2024 and January 2025, against RM3.6 billion a month in 2023–2024. Disbursements to other borrowers barely moved, from RM4.1 billion to RM4.5 billion. BNM flagged the surge as a development requiring vigilance.
The mechanism is mechanical. A pay rise does not reduce civil servants' leverage; it raises the ringgit amount available under the 60% deduction cap, and lenders fill it within weeks. The second phase of the rise took effect in January 2026, and BNM expects it to support household resilience — but also to lift debt through higher loan eligibility. Angkasa's own numbers show it: deduction-authorisation forms jumped from 58,000 in January 2026 to 94,000 in February.
Investor implication: a lender's market share cannot be checked against a published denominator. Use the ones that exist — BNPL against BNM's RM4.9 billion, P2P against SC data, civil-servant financing against Angkasa's monthly deduction run-rate — and treat any "market size" figure in a pitch book as the lender's own estimate.
Pricing
Malaysia has two pricing systems and one convention that hides the difference. Banks and DFIs price payroll-linked personal financing at 5–7%; licensed moneylenders may charge up to 18% a year unsecured. But that 18% is a flat rate, which works out to an effective rate of about 31%.
Table 5 — Selected price points
Sources: BNM; RinggitPlus, CompareHero and Loanstreet product listings; Pawnbrokers Act 1972; KPKT; RAM Ratings; CIMB Securities. SBR is Bank Rakyat's standardised base rate. Effective rates assume equal monthly instalments over the stated term.
The Price of a Deduction Code
On its floating-rate version, Bank Rakyat sells the same civil-servant product at two prices. When the instalment is taken from the payroll before the salary is paid, the spread over its base rate is 2.42–2.77%. When the borrower merely has the salary paid into a Bank Rakyat account, it is 3.78–4.07%. The difference — about 130–136 basis points — is what the segment's largest lender charges for the risk that a borrower diverts the salary.
It is the cleanest market price for payroll access anywhere in this series. It also shows what a payroll lender gives up: a lender that holds a code competes at single-digit rates against a state-backed DFI, so its margin depends on speed and reach rather than on pricing power. RCE Capital's selling point, by its own and analysts' account, is a 48-hour turnaround, not a cheaper rate.
The Flat-Rate Convention
Malaysian consumer credit is routinely quoted as a flat rate: interest calculated on the original principal for the whole term. A standard illustration — RM5,000 over three years at the 18% ceiling — costs about RM214 a month and RM7,700 in total. That is an effective annual rate of about 31%, not 18%. Moneylender, cooperative and hire-purchase rates all need converting before they are compared with bank rates or with yields in other markets. Even Bank Rakyat's fixed-rate civil-servant financing, advertised at 4.92–6.72%, is a flat rate — about 8.6–12.4% in effective terms.
A second ceiling sits inside the first. Moneylenders may not collect total interest exceeding the principal, nor charge compound interest. At 18% flat, that limits an unsecured loan to about five and a half years; at 12%, to about eight years. The cap therefore binds on tenor as well as rate. Pawnbrokers sit under a separate ceiling of 2% a month — about 24% a year — on pledges of up to RM10,000.
Unlike Estonia's ceiling, which resets twice a year with average bank rates, Malaysia's is fixed in statute. With the OPR at 2.75%, the headroom between funding costs and the ceiling is wide; it narrows only if funding costs rise, not if the regulator recalculates.
Kilde view: Payroll deduction compresses price more than it reduces risk. A deduction code makes missed payments rare, but it does nothing about the events that end a deduction — bankruptcy, early retirement, resignation, or a change in which allowances may be deducted. Those losses arrive in blocks rather than as a gradual roll rate. A lender priced at 5–6% because it holds a code has little margin for them; a lender priced at 15–30% without one is paid for a risk that can at least be modelled from repayment data.
{{cta-component}}
Regulatory Framework
Malaysia regulates non-bank credit by product rather than by activity — at least until the Consumer Credit Act 2025 has finished phasing in. Today a lender's supervisor depends on what it lends, to whom, and how it collects.
1. Who Regulates What
Table 6 — Supervisors and statutes
2. The Consumer Credit Act 2025
The Act received Royal Assent on 22 December 2025, was gazetted on 31 December and came into force on 1 March 2026, the same day the Consumer Credit Commission was established. Part V — licensing and registration — took effect on 1 June 2026, with a six-month window for existing providers to comply.
Four provisions matter most to a lender or its financier:
- Licensing with criminal teeth. Carrying on a credit business without a licence is an offence carrying a fine of up to RM5 million, up to five years' imprisonment, or both (section 40). Credit service providers — debt collectors, impaired-loan buyers, debt counsellors — must register (section 57).
- Small businesses count as consumers. Credit of up to RM300,000 to a micro or small enterprise is treated as consumer credit, under an order in force since 1 March 2026. For SME lenders and factoring firms, much of the small-ticket book falls under consumer-protection rules.
- Shariah compliance is a statutory duty. Islamic credit providers must comply with Shariah at all times; rulings of BNM's Shariah Advisory Council bind providers, courts and arbitrators. Breaches carry penalties of up to RM1 million or four years.
- Phased scope. Phase 1 (2025–2027) brings previously unregulated providers under supervision: BNPL, leasing, factoring, debt collection and impaired-loan buyers. Later phases extend the framework to moneylenders, pawnbrokers and car financiers. Providers already supervised by another authority did not need to seek CCA supervision in Phase 1.
The effect is a licensing perimeter closing in stages. The lenders most exposed to the transition are the ones that were unlicensed until June 2026 — BNPL, leasing and factoring firms — and the deadline that matters is the end of the compliance window in December 2026.
3. The Moneylenders Act 1951
KPKT's moneylending regime is old, prescriptive and tightly capped:
- Rates. Up to 12% a year secured and 18% a year unsecured, applied as simple interest; no compound interest; total interest may not exceed the principal; late-payment interest of 8% a year on overdue amounts.
- Contracts. Loans use prescribed forms — Schedule J (unsecured) and Schedule K (secured) under the 2003 licensing regulations. A loan made by an unlicensed lender is unenforceable.
- Collections. Licensed lenders may not hire agents or go to a borrower's home or workplace to collect. Section 29B carries fines of RM50,000–250,000 or three years' imprisonment for repeat offences. Disputes go to civil claims between lender and borrower.
- Scarcity. KPKT approves no more than 60 new moneylending licences a year.
The licence is scarce and the collection toolkit thin. A moneylender's recovery on default is whatever a civil claim recovers, which puts the weight of underwriting on origination rather than collection.
4. The Payroll Channel's Rulebook
Payroll deduction is the market's most valuable collateral and its least codified:
- Only the Accountant General's Department issues deduction codes for the federal payroll. Angkasa's bureau (Biro Perkhidmatan Angkasa) is one of six agencies that process them, alongside BSN and private collection firms.
- Government circulars require civil servants to take home at least 40% of their salary, so total deductions may not exceed 60%.
- The rules move. In 2017 a Ministry of Finance circular capped deductions at 60% of net income and put government loans, such as civil-service housing loans, first in the repayment queue. Lenders had it withdrawn for existing loans after about a month, but both rules still apply to new loans — so a payroll lender ranks behind the government on any borrower who also holds a government loan. In 2025 the Insolvency Department proposed lowering the cap to 55%. One state government disallowed certain allowances from deduction, causing partial defaults that cost RCE Capital a one-off RM3 million impairment.
- Intermediaries matter. RCE phased out the Accountant General's Department as a direct intermediary in favour of its own platforms with Angkasa deduction codes, taking a RM19 million goodwill impairment.
- Fraud is a live risk. The anti-corruption agency's "Op Sky" investigation targeted falsified loan applications by civil servants, and BNM has warned of organised fraudsters persuading borrowers in arrears to refinance into investment scams.
The value of this collateral is set administratively. A lender cannot negotiate the deduction cap, the deductible allowances or the code-issuing process; it can only diversify against changes to them.
5. Cross-Border Lending Rules
Three rules shape any offshore facility:
- Foreign-currency borrowing. A resident company may borrow up to RM100 million equivalent in aggregate — calculated across companies in a parent-subsidiary relationship — from non-resident financial institutions and other unrelated non-residents. That is about US$24 million at current rates. Larger amounts need BNM approval.
- Ringgit borrowing. Ringgit loans from non-resident financial institutions are not permitted, other than through tradable ringgit securities. Other unrelated non-residents may lend up to RM1 million for use in Malaysia.
- Hedging. Residents hedge with onshore licensed banks; exchange-rate derivatives offered by non-residents are not permitted without approval.
Interest paid to non-residents attracts 15% withholding tax, reduced to 10% for Singapore-resident beneficial owners under the Singapore–Malaysia tax treaty in force since 2006.
6. What Changes Next
- December 2026: the six-month compliance window for BNPL, leasing and factoring providers closes.
- 2027 onwards: later phases of the Consumer Credit Act bring moneylenders, pawnbrokers and car financiers under the Commission. Timing has not been published.
- Salary-deduction cap: the Insolvency Department's proposal to cut it to 55% is undecided; a cut without grandfathering would reprice payroll credit overnight.
- Digital banks: GXBank, three years after launch, is seeking early graduation from the RM3 billion asset cap that applies in the foundational phase.
Credit Quality
Malaysia's household impairment ratio is 1.0%, but it is a bank figure. Where non-bank credit quality is measured, it runs at 2.5–4.5%, and the driver differs by collection model.
Table 7 — Credit quality indicators
Sources: BNM Financial Stability Review 2H 2025; AEON Credit filings and RAM Ratings; CIMB Securities and PublicInvest Research on RCE Capital; Malaysian Department of Insolvency via Bernama.
What the Headline Hides
NPL ratios after write-offs. AEON Credit's NPL ratio has stayed between about 2.4% and 2.7% across recent quarters. Its loss rate has not: write-offs in the year to February 2026 equalled about 4.3% of the year-end book, and credit costs averaged 3.8%. In the quarter to May 2026 the write-off ratio rose to 1.4% — about 5.6% annualised — on personal financing and used cars, and management linked rising arrears to cost-of-living pressure on younger and lower-income borrowers. A lender that writes off quickly will always show a low NPL ratio. Ask for write-offs and recoveries by vintage, not the ratio.
Payroll credit fails by exit, not by delinquency. A deduction code makes a missed instalment unlikely. Losses come when the deduction stops: the borrower is declared bankrupt, retires early, resigns, or an allowance is removed from the deductible base. RCE Capital's impairments rose in its 2025 financial year for exactly these reasons, and its non-performing ratio peaked before the 2024–2026 civil-service pay rises helped bring it back to 4.3%.
The bankruptcy data point the wrong way. Civil servants' share of new bankruptcy cases was 12% in 2020, 10% in 2021, 11% in 2022, 13% in 2023 and 14% in 2024 — rising while national bankruptcies fell. In absolute terms the numbers are small — 4,194 civil servants were declared bankrupt between 2020 and June 2025, about 0.3% of a 1.6 million-strong civil service — but for a payroll book the trend matters more than the level. The Insolvency Department also reports debtors seeking bankruptcy deliberately, because the monthly contribution it sets is lower than their loan instalments. For a payroll lender, that is a cap on recoveries chosen by the borrower.
BNPL is small and, so far, clean. Outstanding BNPL debt was RM4.9 billion at end-2025, with 3.2% overdue on a one-day-past-due definition stricter than banks use, down from 6% in March 2023. Active accounts reached 7.5 million, but one consumer can hold several, so account growth overstates user growth.
Stress
BNM's stress test puts up to 5.3% of banking-system household loans at risk of default by end-2028 if unemployment rises to 6%, against 2.9% today. Lower-income and highly indebted borrowers with thin buffers are the most exposed — the same segments that non-bank lenders serve.
What would break the thesis: the view that payroll credit is a low-loss asset fails if the deduction cap is cut without grandfathering existing loans, or if civil servants' share of bankruptcies keeps rising after the January 2026 pay rise. The Insolvency Department's annual data for 2025 and 2026 is the test.
Major Players
The Malaysian non-bank market is concentrated at the top and fragmented below. One lender, AEON Credit, has a book above RM16 billion; the next listed specialist, RCE Capital, has RM2.1 billion. Below them sit thousands of licensed moneylenders and cooperatives with no published accounts.
Table 8 — Market map
Sources: AEON Credit filings and RAM Ratings; RCE Capital and analyst reports; The Edge; SC; BNM; KPKT via FMT. Bank Rakyat figures from its June 2025 interim statements and FY2025 results.
Who Is Actually Investable
AEON Credit is a benchmark, not an opportunity. It has investment-grade sukuk, a Japanese parent, a three-year average net interest margin of 12.1% and funds itself more cheaply onshore than any offshore facility could offer. Its value to an investor is as a reference point: credit costs averaging 3.8% and rising write-offs among younger, lower-income borrowers show where Malaysian non-prime credit stands in 2026.
RCE Capital is the template for payroll credit. By 2020 it had raised about RM2.9 billion of securities backed by civil-servant personal financing, starting in 2004. On recent tranches, senior classes carry AAA ratings with overcollateralisation of 163–293% as at December 2025. The domestic market already prices payroll receivables as near-sovereign; an offshore lender will not beat that on price.
The gap is the middle. Lenders with books of roughly RM50–500 million sit in it: licensed moneylenders with online approvals, cooperative-channel originators without their own securitisation programme, and factoring and BNPL firms working through their Consumer Credit Commission licences. They are too small for the sukuk market and too specialised for unsecured bank lines.
Kilde view: In Malaysia the investable counterparty is defined by its collection mechanism, not its product. A lender whose collections depend on a deduction code it does not own — one held by a cooperative partner or an intermediary — carries a counterparty risk its loan tape will not show. We would want the code-holding entity inside the security package, or a direct collection agreement with it, before lending against payroll receivables.
The Funding Stack
Malaysia has one of the deepest local-currency bond markets in Asia, and its largest non-bank lenders use it: AEON Credit funds through a RM5 billion sukuk programme, RCE Capital through rated asset-backed sukuk. That changes the question an offshore facility has to answer. It is not "is there funding?" but "who cannot reach it?"
Table 9 — Funding channels
Sources: AEON Credit quarterly report (Feb 2026) and RAM Ratings; RAM Ratings via BIX Malaysia; SC Annual Report 2025; BNM foreign-exchange notices.
The Arithmetic of an Offshore Facility
Take a US-dollar senior secured facility at 12%. Withholding tax of 10%, normally grossed up by the borrower, adds about 1.3 points to its cost. Hedging into ringgit, at current one-year forward points, gives back roughly 1.0–1.3 points. The borrower's all-in ringgit cost lands near 12% — against an analyst-assumed cost of funds of about 5% for RCE Capital, and less for AEON Credit.
An offshore facility cannot win on price with lenders that reach the sukuk market. It wins with lenders that cannot, by offering three things the domestic stack does not:
- Size in the gap between P2P tickets and a rated programme — typically RM20–100 million, which also fits inside the foreign-currency cap.
- Speed — weeks rather than a rating cycle, which matters to a lender racing the Consumer Credit Commission's December 2026 deadline.
- Structure — borrowing-base facilities secured on assigned receivables, with eligibility rules written around how Malaysian loans actually fail (for payroll books, suspended deductions rather than days past due).
The Cross-Border Route
Because offshore financial institutions cannot lend in ringgit except through tradable securities, the facility is in US dollars. The RM100 million cap applies to all foreign-currency borrowing from unrelated non-residents across the borrower's group, so a lender with existing offshore lines may have less headroom than its balance sheet suggests.
Investor implication: ask for the group's aggregate foreign-currency borrowing schedule before the term-sheet stage, and make a headroom certificate a condition of each drawdown. The hedge sits with the borrower's onshore bank; evidence of it should be a drawdown condition too.
Market Risks
The risks that would break a Malaysian non-bank thesis are administrative and behavioural rather than macroeconomic. Growth, inflation and the sovereign are not where losses would come from.
1. Regulatory
Table 10 — Regulatory risks
2. Credit and Fraud
Table 11 — Credit signals to monitor
3. Funding and Foreign Exchange
- Headroom risk. The RM100 million group cap on foreign-currency borrowing can bind before a lender's balance sheet does.
- Carry reversal. The hedge pays the borrower only while ringgit rates sit below US rates. Most economists expect BNM to start normalising in 2027, and each 25 bp hike trims the carry by roughly the same amount; US easing would narrow it further.
- Oil and subsidies. Subsidy spending reached 18% of the operating budget in Q1 2026, and S&P notes the bill could rise further with the 2026 oil shock. A subsidy cut would hit lower-income borrowers' cash flow directly.
4. Outlook
The base case for 2026–27 is benign: growth near 5%, inflation below 2%, an OPR that economists expect to hold at 2.75% to the end of 2026 before a gradual normalisation in 2027 (OCBC pencils in 3.00% for January), and a civil-service pay rise that lifts repayment capacity. In that case the main event is regulatory — the Consumer Credit Commission's first licensing round — rather than credit.
What would change the view: a cut to the 60% deduction cap without grandfathering; civil servants' share of new bankruptcies above 15%; BNPL arrears back above 5%; or ringgit rates rising above US rates, which would turn hedge carry negative.
{{cta-component}}
Opportunities for Private Credit Investors
Malaysia is a market for selective, structured lending to mid-tier specialists, not for broad exposure. Each route below has one diligence question that decides it.
Table 12 — Entry routes
Note: directional only. Ranges assume senior secured, short-tenor US-dollar facilities with a borrowing base on eligible receivables, receivables assignment, cash sweep, and covenants on leverage, portfolio quality and foreign-currency headroom, as described in this report. They are investor coupons before fees, not offers or quotes, and actual pricing depends on the borrower. As a reference point, Kilde's own tranches for a Malaysian consumer-instalment lender issued since December 2025 carry coupons of 13.5–14.0% (US dollar and Singapore dollar, 13–37-month bullet, secured on the loan portfolio), and those for a regional lender with Malaysian exposure 12.25–13.0%. Payroll-financing originators can fund onshore at about 5%, which is why the first route sits at the low end and may find few takers.
Mitigating the Malaysia-Specific Risks
- Collection control. Put the code-holding entity in the security package, or obtain a direct collection agreement with it.
- Eligibility that matches how loans fail. Exclude accounts whose deductions have been suspended from the borrowing base, whatever their days past due.
- Concentration limits by employer type (federal, state, statutory body), by state and by allowance type.
- Licence conditions. For BNPL, leasing and factoring borrowers, make a Commission licence — or a filed application before the deadline — a condition precedent and a continuing covenant.
- Foreign-exchange discipline. Require a group foreign-currency headroom certificate and evidence of the onshore hedge at each drawdown.
- Tax. Withholding-tax gross-up, with a Singapore tax-residence certificate to secure the 10% treaty rate.
- Write-off transparency. Covenant on write-offs and recoveries by vintage, not only on NPL ratios.
Kilde view: Malaysia's opportunity is narrow and real. The domestic market prices payroll credit as near-sovereign, and moneylending is capped and fragmented. The lenders worth financing sit between those poles: specialists with RM50–500 million books, licences in hand under the new Act, and collections they control themselves. For them, a facility that closes in weeks and fits inside the foreign-currency cap is worth more than the price gap to a sukuk they cannot yet issue.
How Malaysia Compares
Table 13 — Malaysia against other Asian markets in the series
Sources: Kilde's analyses of the Philippines, Indonesia and India; national regulators. Latest available, not always the same date.
Malaysia sits at the developed end of Kilde's market reports: among the Asian markets compared here, it has the lowest policy rate, a capital market as deep as India's, and is the only one where hedging pays the borrower. The same features make it the hardest for an offshore lender. Its strongest non-banks fund locally, so the opportunity is confined to the tier below them.
Conclusion
The numbers describe a strong economy carrying a heavy household balance sheet. Growth was 6.0% in Q2 2026, inflation is under 2% and the policy rate is 2.75%. Household debt is 84.8% of GDP, and about RM300 billion of it sits outside the banks in a sector no regulator measures as a whole.
The distinctive risk is administrative. Malaysia's best non-bank collateral is a payroll deduction code, and its value is set by government circulars on the deduction cap and deductible allowances. Losses arrive through exits from the payroll — bankruptcy, early retirement, resignation — and civil servants' share of bankruptcies has risen every year since 2021. A cut to the 60% cap without grandfathering is the event that would reprice the whole segment.
The distinctive opportunity is the middle tier. The Consumer Credit Act 2025 is converting BNPL, leasing and factoring firms into licensed lenders, and moneylenders will follow. Those that come through licensed, with RM50–500 million books and collections they control, are too small for the sukuk market. For them, a fast, well-structured US-dollar facility is worth more than its price — and in Malaysia, unusually for emerging Asia, the hedge works in the borrower's favour.
About Kilde
At Kilde, we specialise in secured private credit — and that is all we do.
Kilde is a regulated investment platform that helps accredited investors earn a predictable monthly income through high-yield, senior-secured private credit. We deal exclusively with licensed non-bank financial institutions with a proven track record and strong financial performance. Each borrower is vetted using Kilde's proprietary credit scoring model, which analyses over 20 million data points on loans and repayments.
Our investments typically run 3 to 36 months with collateral coverage above 100%. Monthly cash coupons provide predictable income, and an early redemption option on select deals offers additional flexibility. Strict covenants on leverage, interest coverage and repayment rates protect investor capital throughout the tenure, with continuous monitoring of borrower performance and loan agreements under Singapore law.
Where conventional fixed income forces a choice between low-risk, low-return safety and higher-risk vehicles, Kilde's model delivers strong yields with disciplined risk management.
Sources
{{sources}}
- Bank Negara Malaysia, Financial Stability Review 2H 2025 — Credit Risk. https://www.bnm.gov.my/publications/fsr2025h2/ch1b
- Bank Negara Malaysia, Financial Stability Review 2H 2025 — The Banking Sector. https://www.bnm.gov.my/publications/fsr2025h2/ch2a
- Bank Negara Malaysia, Financial Stability Review 1H 2024. https://www.investmalaysia.gov.my/media/nwano5ab/bnm-financial-stability-review-1h2024.pdf
- Bank Negara Malaysia, Financial Stability Review 2H 2023, box on non-bank financial institutions. https://www.bnm.gov.my/documents/20124/13790687/fsr23h2_en_box1.pdf
- Bank Negara Malaysia, Spotlight: Household Debt (FSR 2H 2021). https://www.bnm.gov.my/documents/20124/6459002/fsr21h2_en_hhdebt.pdf
- Bank Negara Malaysia, Economic and Financial Developments in Malaysia in the Second Quarter of 2026. https://www.bnm.gov.my/-/gdp2q26pr
- Department of Statistics Malaysia, Gross Domestic Product Second Quarter 2026. https://www.dosm.gov.my/portal-main/release-content/gross-domestic-product-q22026
- Ministry of Finance, Press release on Q2 2026 GDP (14 August 2026). https://www.mof.gov.my/portal/images/2026/08/14/Press-Release-Q2-2026-GDP-14082026.pdf
- Ministry of Finance, Fitch affirms Malaysia at BBB+ (December 2025). https://mof.gov.my/portal/images/2025/12/09/Press-Release-Fitch-Ratings-Affirms-Malaysia-Sovereign-Credit-Rating-Outlook-Stable.pdf
- Ministry of Finance, Credit providers require licensing and registration effective 1 June 2026. https://www.mof.gov.my/portal/en/news/press-citations/credit-providers-credit-service-providers-require-licensing-registration-effective-june-1
- Ministry of Housing and Local Government (KPKT), Community Credit Control Division FAQ. https://www.kpkt.gov.my/index.php/pages/view/585
- Securities Commission Malaysia, Annual Report 2025 media release. https://www.sc.com.my/resources/media/media-release/malaysian-capital-market-hits-record-rm43-trillion-in-2025
- Bank Negara Malaysia, Liberalisation of the Foreign Exchange Administration Rules. https://www.bnm.gov.my/-/liberalisation-of-the-foreign-exchange-administration-rules-2
- Inland Revenue Board of Malaysia, Withholding tax. https://www.hasil.gov.my/en/legislation/withholding-tax/
- Ministry of Finance Singapore, Singapore–Malaysia tax agreement enters into force (2006). https://www.mof.gov.sg/news-resources/newsroom/new-agreement-between-singapore-and-malaysia-for-the-avoidance-of-double-taxation-and-the-prevention-of-fiscal-evasion-comes-into-force/
- Trading Economics (Kilde data feed), Malaysia and United States indicators: OPR, Fed funds, CPI, unemployment, population, GDP, reserves, USD/MYR, BIS household debt series. Accessed 12 October 2026.
- Lexology, Consumer Credit Act 2025 comes into operation (2 March 2026). https://www.lexology.com/library/detail.aspx?g=2d009d2e-7908-463c-a788-49ad5ff1b2e4
- Conventus Law (Azmi & Associates), Navigating Malaysia's New Credit Frontier under the Consumer Credit Act 2025 (26 August 2026). https://conventuslaw.com/report/navigating-malaysias-new-credit-frontier-under-the-consumer-credit-act-2025/
- DFDL, Malaysia: A Summary of the Consumer Credit Act 2025. https://www.dfdl.com/insights/content-hub/articles/malaysia-a-summary-of-the-consumer-credit-act-2025/
- RHB Group, Foreign Exchange Administration Rules summary. https://www.rhbgroup.com/others/highlights/foreign-exchange-administration-rules/index.html
- Trowers & Hamlins, Malaysia: Revised Foreign Exchange Notices (2021). https://www.trowers.com/insights/2021/june/malaysia-revised-foreign-exchange-notices
- AEON Credit Service (M) Bhd, Announcements (results to 31 August 2026). https://aeoncredit.com.my/annoucements/
- AEON Credit Service (M) Bhd, Q4 FYE2026 analyst presentation. https://aeoncredit.com.my/wp-content/uploads/AEON-Credit-Analyst-Presentation-Q4FYE2026.pdf
- AEON Credit Service (M) Bhd, Quarterly report to 28 February 2026. https://newsfile.moomoo.com/public/NN-PersistNoticeAttachment/7781/20260407/MYX/MYX_3652766_237750.pdf
- RAM Ratings via BIX Malaysia, AEON Credit sukuk ratings affirmed. https://www.bixmalaysia.com/news-announcements/announcement-details?id=81723
- RAM Ratings via BIX Malaysia, Zamarad and Al Dzahab sukuk rating actions (19 May 2026). https://bixmalaysia.com/news-announcements/announcement-details?id=81033
- RAM Ratings via IslamicMarkets, Zamarad Tranche 5 sukuk (2020). https://islamicmarkets.com/publications/ram-ratings-assigns-preliminary-ratings-to-tranche-5-sukuk-issued
- CIMB Securities, RCE Capital 4QFY3/26 results (28 May 2026). https://rce.com.my/docs/news/20260528_CIMB_4Q26.pdf
- PublicInvest Research, RCE Capital 1QFY27 results (12 August 2026). https://klse.i3investor.com/web/blog/detail/PublicInvest/2026-08-12-story-h502314020-RCE_Capital_Berhad_Lifted_by_Lower_Impairments
- RCE Capital Bhd, Company overview. http://ir.chartnexus.com/rce/management_discussion_and_analysis.php
- RinggitPlus, Bank Rakyat Personal Financing-i Public. https://RinggitPlus.com/en/personal-loan/Bank-Rakyat-Personal-Financing-i-Public.html
- RinggitPlus, Yayasan Ihsan Rakyat Personal Financing-i. https://ringgitplus.com/en/personal-loan/Yayasan-Ihsan-Rakyat-Personal-Financing-i.html
- The Star, Household debt at RM1.73 trillion, 84.4% of GDP (1 July 2026). https://www.thestar.com.my/news/nation/2026/07/01/household-debt-at-rm173-trillion-844-of-gdp-but-loan-defaults-remain-low-says-anwar
- The Star, S&P affirms sovereign ratings, stable outlook (30 September 2026). https://www.thestar.com.my/business/business-news/2026/09/30/sp-affirms-sovereign-ratings-stable-outlook
- The Edge Malaysia, S&P maintains Malaysia at A- (29 September 2026). https://theedgemalaysia.com/node/819709
- New Straits Times, Moody's keeps Malaysia at A3 (14 July 2026). https://www.nst.com.my/amp/business/economy/2026/07/1488798/moodys-keeps-malaysia-a3-backs-2026-growth-outlook
- Malay Mail, Civil servants pay RM14.4b a year for personal loans (8 April 2024). https://www.malaymail.com/news/malaysia/2024/04/08/report-civil-servants-pay-rm144b-a-year-for-personal-loans-more-borrowing-this-aidilfitri/127896
- The Edge Malaysia, Personal financing to civil servants surges after salary hike (citing BNM). https://theedgemalaysia.com/node/748967
- The Edge Malaysia, Newsbreak: Lenders avert move that would have hurt their personal lending business (9 October 2017). https://theedgemalaysia.com/article/newsbreak-lenders-avert-move-would-have-hurt-their-personal-lending-business
- The Edge Malaysia, Bank Rakyat puts brakes on growth of personal loans. https://theedgemalaysia.com/article/bank-rakyat-puts-brakes-growth-personal-loans
- Bernama, 10–13% of new bankruptcy cases from 2021–2024 involve civil servants (8 September 2024). https://www.bernama.com/en/news.php?id=2338336
- Malay Mail, Rising bankruptcy cases prompt reform proposals (25 March 2025). https://www.malaymail.com/news/malaysia/2025/03/25/how-much-debt-can-civil-servants-take-rising-bankruptcy-cases-prompt-reform-proposals/169492
- Free Malaysia Today, Going bankrupt on purpose to avoid high loan repayments (18 January 2025). https://fmtv5.freemalaysiatoday.com/category/nation/2025/01/18/going-bankrupt-on-purpose-to-avoid-high-loan-repayments
- Free Malaysia Today, Lower civil servants' salary deduction cap, says expert (25 February 2025). https://www.freemalaysiatoday.com/category/nation/2025/02/25/lower-civil-servants-salary-deduction-cap-says-expert
- The Star, Civil service test for RCE (1 September 2025). https://www.thestar.com.my/business/business-news/2025/09/01/civil-service-test-for-rce
- CB Insights, RCE Capital (citing CIMB Securities on AGD phase-out and Op Sky). https://www.cbinsights.com/investor/rce-capital
- Free Malaysia Today, Event for licensed moneylenders (licence counts, 22 November 2024). https://www.freemalaysiatoday.com/category/nation/2024/11/22/event-for-licensed-moneylenders-mocked-for-ah-long-link
- The Edge Malaysia, KPKT approves no more than 60 moneylending licences a year. https://theedgemalaysia.com/node/687448
- The Edge Malaysia, AEON Credit to rein in bad loans — RHB (13 July 2026). https://theedgemalaysia.com/node/810395
- The Edge Malaysia, GXBank pursues early graduation (21 September 2026). https://theedgemalaysia.com/node/818902
- Fintech News Malaysia, SC Malaysia Annual Report 2025: five things to know. https://fintechnews.my/58007/wealthtech-malaysia/sc-malaysia-annual-report-2025-fintech/
- iMoney, Earning under RM3,000 and need a loan? (flat-rate illustration). https://www.imoney.my/articles/low-income-loan-safe-guide
- bne IntelliNews, Malaysia's digital banks lure 2mn customers (21 August 2026). https://www.intellinews.com/malaysia-s-digital-banks-lure-2mn-customers-as-big-lenders-keep-their-grip-461179/
- Investing.com, USD/MYR forward rates (delayed quote, early August 2026). https://www.investing.com/currencies/usd-myr-forward-rates
- Federal Reserve Bank of St. Louis (FRED), 1-Year Treasury Constant Maturity, DGS1 (8 October 2026). https://fred.stlouisfed.org/series/dgs1
- Bank Negara Malaysia, KLIBOR data download (September 2026). https://financialmarkets.bnm.gov.my/data-download-klibor
- Hong Leong Bank, Published reference rate: 3M KLIBOR 3.55% effective 6 October 2026. https://www.hlb.com.my/en/personal-banking/help-support/interest-rates/reference-rate.html
- TradingView, Malaysia 1Y government yield (MY01Y). https://in.tradingview.com/symbols/TVC-MY01Y
- Utusan Malaysia, Hampir sejuta penjawat awam berhutang (Angkasa deduction data, 14 March 2026). https://www.utusan.com.my/nasional/2026/03/pinjaman-penjawat-awam-meningkat-20-peratus-dalam-sebulan/
- Bank Rakyat, Consolidated interim financial statements for the financial half year to 30 June 2025. https://www.bankrakyat.com.my/uploads/content-downloads/file_20250825180142.pdf
- The Edge Malaysia, Bank Rakyat declares 18% dividend for FY2025 (April 2026). https://theedgemalaysia.com/node/800100
- Business Today, Bank Rakyat delivers FY25 profit as total assets hit RM131 billion (16 April 2026). https://www.businesstoday.com.my/2026/04/16/bank-rakyat-delivers-stellar-fy25-profit-solid-dividend-as-total-assets-hit-rm131-billion/
- RTM Berita, Nilai pasaran industri kredit komuniti cecah RM24.8 bilion (May 2024). https://berita.rtm.gov.my/nasional/senarai-berita-nasional/senarai-artikel/jangan-pinjam-wang-along-kor-ming/
- Bernama, Nilai pasaran kredit komuniti negara cecah RM24.8 bilion (May 2024). https://www.bernama.com/bm/news.php?id=2300972
- Ministry of Finance, Malaysia records strongest second-quarter growth outside pandemic period since 2014 (14 August 2026). https://mof.gov.my/portal/en/news/press-release/malaysia-records-strongest-second-quarter-growth-outside-pandemic-period-since-2014
- Business Today, BNM on hold but changes in tone, OCBC sees OPR raised to 3% in January (3 September 2026). https://www.businesstoday.com.my/2026/09/03/bnm-on-hold-but-changes-in-tone-ocbc-sees-opr-raised-to-3-in-january/
- The Edge via KLSE Screener, Economists see BNM holding OPR through 2026, with gradual rate normalisation next year (9 July 2026). https://cdn.klsescreener.com/v2/news/view/1752691/economists-see-bnm-holding-opr-through-2026-with-gradual-rate-normalisation-next-year
- Bank Negara Malaysia, Financial Stability Review 2H 2019, Credit Risk (household debt definition; LPPSA). https://www.bnm.gov.my/documents/20124/2724391/fsr2019h2_en_ch1a.pdf
- CEIC, Malaysia bank lending rate (BNM weighted average). https://www.ceicdata.com/en/indicator/malaysia/bank-lending-rate
- CompareHero, Bank Rakyat Personal Financing-i Public (fixed-rate repayment table). https://www.comparehero.my/personal-loan/product/bank-rakyat-personal-financing-i-public/
- Loanstreet, Government/GLC personal loans (profit vs effective rates). https://loanstreet.com.my/personal-loan/government
- RinggitPlus, Licensed moneylenders and pawnbrokers agree to 3-month moratorium (pawnbroker rate ceiling, via Bernama). https://ringgitplus.com/en/blog/personal-finance-news/licensed-moneylenders-and-pawnbrokers-agree-to-3-month-moratorium.html
- The Vibes, Pawnbrokers: lifeline or death knell for the poor (Pawnbrokers Act 1972, sections 3 and rate of profit). https://www.thevibes.com/articles/opinion/16818/pawnbrokers-lifeline-or-death-knell-for-the-poor-sothi-rachagan
Disclaimer Notice
This page is provided for general informational purposes only and does not constitute legal, financial, or investment advice. Please refer to our Full Disclaimer for important details regarding eligibility, risks, and the limited scope of our services.
FAQ
Yes, in foreign currency. Under BNM's foreign-exchange rules a Malaysian company may borrow up to RM100 million equivalent in aggregate, on a group basis, from non-resident financial institutions and other unrelated non-residents without approval. Ringgit loans from offshore financial institutions are not permitted except through tradable securities, so facilities are usually in US dollars, hedged onshore by the borrower. Interest attracts 15% withholding tax, or 10% for Singapore-resident lenders.
The deduction stops. Once a bankruptcy order is made, the borrower pays a monthly contribution set by the Insolvency Department, which is distributed among creditors and is usually far lower than the original instalment. The lender becomes one unsecured creditor among many. That is why payroll lenders' losses track bankruptcies, early retirements and resignations rather than missed payments.
Yes. Moneylenders need a licence from the Ministry of Housing and Local Government under the Moneylenders Act 1951, and the ministry approves no more than 60 new licences a year. A loan made by an unlicensed lender is unenforceable. Separately, the Consumer Credit Act 2025 makes running a credit business without a required licence a criminal offence, with fines of up to RM5 million, up to five years' imprisonment, or both.
No. Conventional and Islamic finance run side by side, and Shariah-compliant financing makes up about 40% of the banking market. Much payroll and personal financing is nonetheless structured as Islamic, and the Consumer Credit Act 2025 makes Shariah compliance a statutory duty for Islamic credit providers, bound by rulings of BNM's Shariah Advisory Council. A financier lending against such receivables should confirm the structure carries Shariah sign-off.
Partly. Credit of up to RM300,000 extended to a micro or small enterprise is treated as consumer credit, under an order that took effect on 1 March 2026. Factoring and leasing are also licensable credit businesses under the Act. An SME lender with many small tickets should therefore expect much of its book to fall within the Act's conduct and licensing rules.
The largest ones do: AEON Credit combines bank term financing with a rated sukuk programme, and RCE Capital securitises its payroll receivables. Below that tier, banks are cautious about unsecured consumer books without a rating, and the sukuk market needs scale, a rating and a seasoned pool. Mid-sized lenders rely instead on equity, short bank lines and P2P platforms — the gap private credit fills.